
0
Follow
0
Followers
볼린저 밴드, TA.BOLL에서 얻은 볼린저 밴드 데이터가 K-라인을 보고 얻은 볼린저 밴드 데이터와 왜 그렇게 다른가요? 도와주세요
Created 2021-02-25 19:47:20
6
1507
브린 데이터 코드를 가져오기
def get_boll(self, period = PERIOD_M1 ,variance = 2):
self.upLine = '---'
self.midLine = '---'
self.downLine = '---'
r = exchange.GetRecords(period)
if r and len(r) > 20:
boll = TA.BOLL(r, 20, 2)
self.upLine = boll[0]
self.midLine = boll[1]
self.downLine = boll[2]
log는 2021-2-23 19:10의 브린 상중 하향 레일 제1,2,3,의 값은 다음과 같습니다.
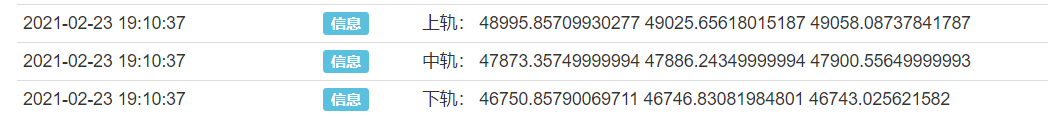
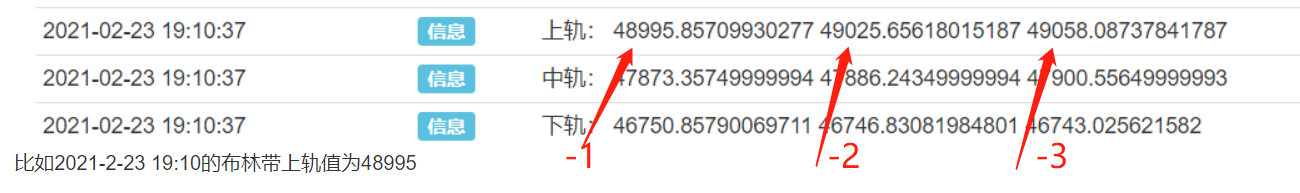
예를 들어 2021-2-23 19:10의 브린 벨트 오브 오바일 값은 48995이다.
하지만 K선으로 돌아보면, 1분 BB[20,2]의 오프레일 값은 48457입니다.
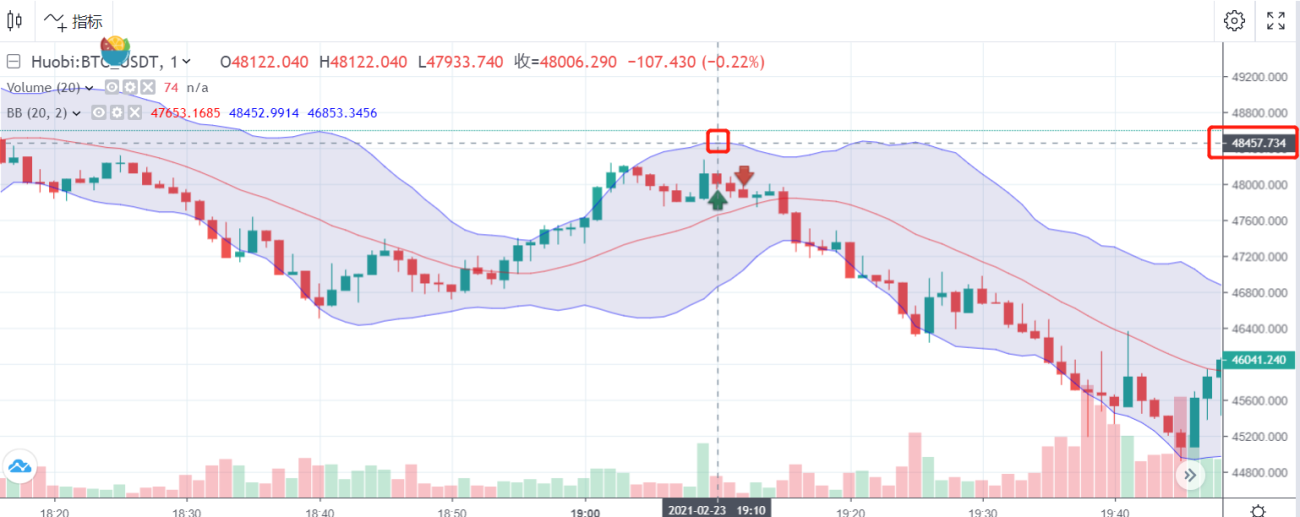
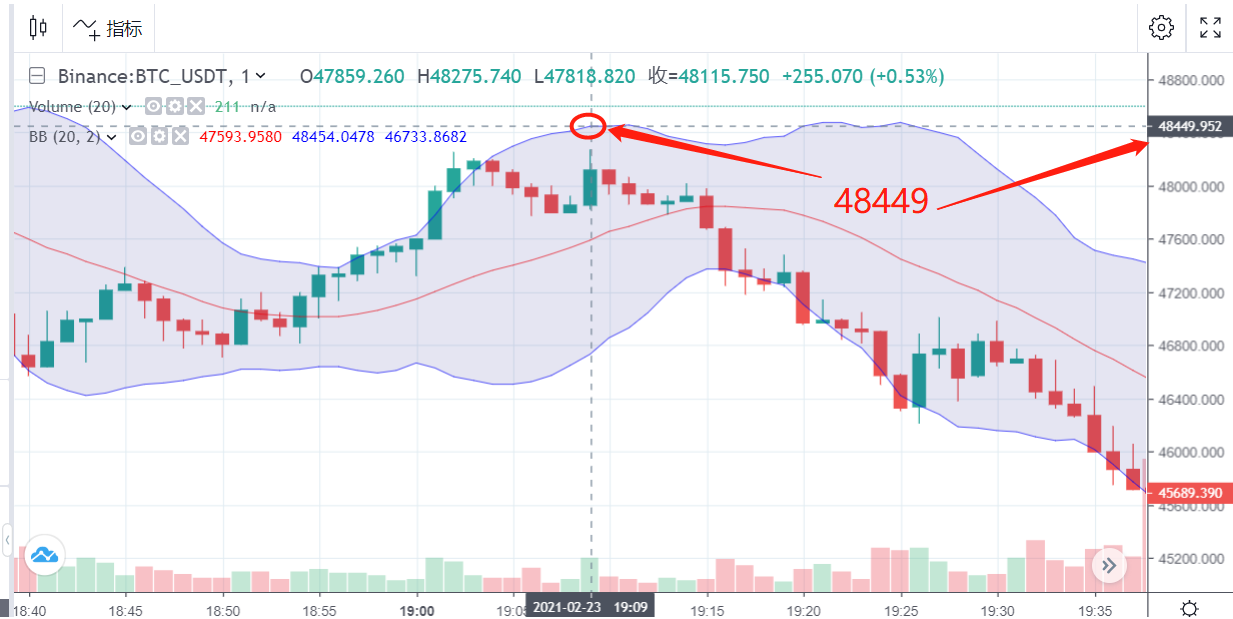
두 값이 500개 이상 틀렸어요. 토큰의 K선, 1분 K선 BB ((20,2) 의 상궤도 값도 48457개 정도였죠.
저는 제가 문제를 사용해야 한다는 것을 알고 있지만, 문제는 어디에 있는지, 도움을 요청합니다.
Related Recommendations
How to Specify Different Versions of Data for the Rented Strategy by Its Rental Code MetadataAdvanced Tutorial for FMZ Quant platform Strategy WritingElementary Tutorial for FMZ Quant platform Strategy WritingGet Started with FMZ Quant PlatformSECURITY BUGI keep getting error: Exchange_GetAccount: Invalid ContractTypeWe have an incredibly profitable market making algorithm for sideways markets on Bitmex - but need expert to help eliminate wait times during downward volatility in the marketError with deribitLimitations of the backtesting engineHow to install ta-lib on linux docker?
Comment
All comments (6)


- 1